Examining Thailand's Fintech Landscape
Liam Turner
Editorial · Sep 07, 2026
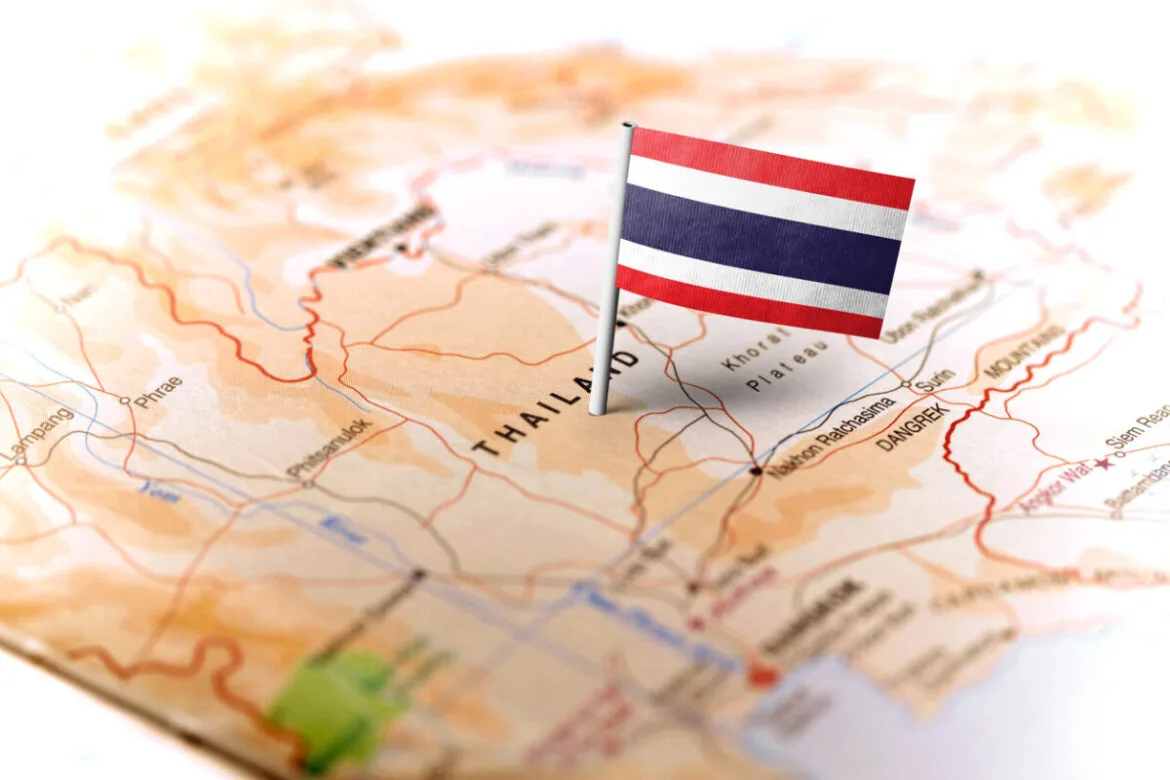
Editorial Calendar Exclusive Content Feature Stories Examining Thailand’s Fintech Landscape The second-largest economy in the Association of Southeast Asian Nations (ASEAN) region after Indonesia, has a gross domestic product (GDP) per capita of just shy of $7,000 per person, making Thailand a high-middle-income economy. With a population of over 70 million people, Thailand’s capital and largest city, Bangkok, is world-renowned as a popular destination for tourists. Much of the success of Thailand’s ecosystem can be attributed to government-led initiatives and market demand.
Thailand’sNational Economic and Social Development Plan 2023–2027(NESCD) aims to transform Thailand into a circular economy (CE) and a low-carbon society. This plan outlines three main targets for economic progress by 2027: Achieving a minimum of one per cent contribution of the CE to GDP growth Reducing domestic material consumption by at least 25 per cent Increasing material circularity indicators for specific products by at least 10 per cent Thailand’s digital transformation is being driven, in part, by fintechs. Similar to other regions across Asia, mobile payments are now preferred as a payment method over card payments by 70 per cent of Thai consumers.
QR codes have also become apopular payment method in Thailand. Looking beyond Thai borders, theBank of Thailandhas revealed a plan to introduceQR code cross-border paymentswith India by the third quarter of this year. Over 94 per cent of Thai consumers have used digital systems to pay for services, with the most used method being digital wallets, according toMastercard’sNew Payments Index 2022.
Thailand’s fintech ecosystem boasted over$28billionin assets under management (AUM) in 2023. Although not quite as big as other neighbouring countries such as Singapore, Thailand’s fintech sector continues to grow. In 2017,Kasikorn Bank(KBank) set up theKasikorn Business-Technology Group (KBTG)to operate as the tech development and IT infrastructure wing of the KBank group.
The same year,
← Previous
Sponsor Banks, BaaS, and Plugging Digital Assets into the Banking System
Next →
UK Payments Leaders Favour Evolution Over a Clean-Sheet Rebuild