Sponsor Banks, BaaS, and Plugging Digital Assets into the Banking System
Liam Turner
Editorial · Sep 08, 2026
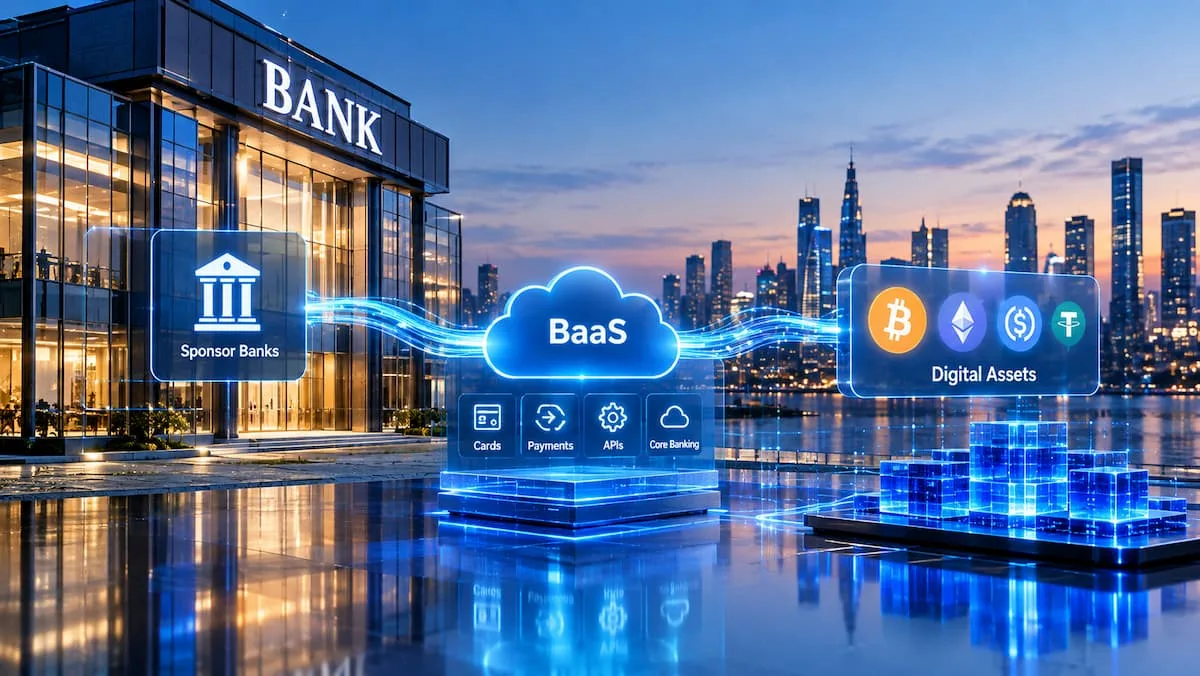
Part 3 shifts the focus from licensing categories to infrastructure. Once a company has selected its regulatory approach, the practical question is how to connect that structure into the traditional payments system. Sponsor banks and banking-as-a-service (BaaS) arrangements are common tools for doing so.
They can allow a digital asset or FinTech business to access core banking functions and payment rails without obtaining a bank charter or rebuilding the entire regulatory stack in-house. Used thoughtfully, they can accelerate launch and extend product capabilities. Used reflexively, they can create dependencies that are difficult to unwind and that effectively lock the company into a particular regulatory lane.
The throughline remains speed to market. The aim is to reach customers quickly while preserving flexibility for how the regulatory and infrastructure stack evolves over time. A sponsor bank relationship allows a non-bank FinTech to provide a customer-facing experience for banking products offered through a chartered institution.
The bank is not merely a back-end provider and cannot be treated as a fully white-labeled institution from a regulatory or contractual perspective. It provides the regulated product, holds customer funds on its balance sheet, opens and maintains accounts (often through omnibus or for-benefit-of structures), and connects to payment systems such as ACH, Fedwire, RTP, and card networks. It is subject to the full suite of banking supervision, including safety-and-soundness, consumer protection, and BSA/AML obligations.
The FinTech may design the user experience, build the app or platform, and perform substantial operational and compliance functions under the bank’s oversight. But the user relationship must reflect the bank’s role in the regulated product. The customer will need contractual privity with the bank in some form often through pass-through terms in the FinTech’s agreements and, increasingly, through direct contractual terms between the customer and the bank.
The bank must be clearly
← Previous
Paymob Secures $35 Million Pre-Series C Co-Led by Mubadala and EBRD to Accelerate MENA Expansion
Next →
Examining Thailand's Fintech Landscape
Related Reading
Jordan Kuwait Bank issues $100m Green Bond with IFC backing
Sep 28, 2026
European Corporate Treasury Pivots to Mobile as Bank of America's CashPro Surpasses €100B in Approved Payments
Sep 28, 2026
Interpolitan Money Warns Banks are Misreading Complexity as Risk
Sep 27, 2026